What 10-year structural insurance is, what it covers and how insurers usually respond.

10-year structural insurance
What 10-year structural insurance is
What amount the 10-year structural insurance must cover.
What 10-year structural insurance is
10-year structural insurance (seguro decenal) is the insurance policy that the developer of a building project must take out to cover structural damage for a period of 10 years, under article 9.c) of the LOE.
Structural damage means material damage caused to the building by flaws or defects that originate in or affect the foundations, supports, beams, floor slabs, load-bearing walls or other structural elements, and that directly compromise the mechanical strength and stability of the building. In other words, the most dangerous and serious damage a building can suffer.
It is therefore the obligation of the professional developer to take out this insurance with cover for such damage for a period of 10 years; indeed, without it, the new building cannot be formally declared (declaración de obra nueva) nor can the developer be wound up (under article 20 of the LOE).
What is more, to prove it, in the declaration of the new building a copy of the policy must be presented to the notary together with a certificate issued by the insurer confirming that the contract has been taken out and is in force.
The 10-year structural insurance in turn usually requires the developer to engage an impartial OCT (Technical Control Body) to verify that everything has been built correctly, so that the insurance company will then answer for structural damage for 10 years.
What amount the 10-year structural insurance must cover.
According to the Resolutions of the DGRN (Directorate General of Registries and Notaries) of 21 March 2007 and 4 May 2007, the cover required of 10-year structural insurance against structural damage is not based on the value attributed to the building in the declaration of the new building, but on the construction cost “ the concepts of material construction cost and value of the new building are not equivalent. The final material construction cost, including professional fees, refers to the sum of the amounts of the resources used to carry out the works, which is the amount that must be insured, whereas the concept of value of the new building refers to a greater reality; it is a broader concept that includes not only the construction cost but other aspects, mainly the increase or added value of the construction, an added value determined by a series of concurrent and diverse circumstances such as the market, the surroundings, the location and the internal and external characteristics of the building itself, resulting, consequently, in a figure that does not coincide with the strict material cost of carrying out the works…”.
How insurers usually respond.
The problem is that, when claims are made, 10-year structural insurance companies, unless the matter is blatantly obvious, usually respond that the claim is not covered because the problems are not structural, attributing them to other, less serious types of damage, or respond that they originate from external causes beyond their liability (such as damage caused by burst supply pipes, adjoining building works, etc.) in order to reject the claim and avoid paying.
The best course of action is therefore first to commission a rigorous expert report to determine the origin of the damage. If it is structural damage, a claim can be made directly against the 10-year structural insurance. However, in any event you can always sue the developer as seller of the building, since whether the damage is structural, a habitability issue or a simple breach of contract, it must answer to the buyers of the homes in any case. And if the damage is indeed structural, the developer can “bring in” the 10-year structural insurance company as a party, or exercise its right of recourse against it.
If you have a problem with 10-year structural insurance, contact us.
Related articles
Drain smells and home drainage systems: why your home smells of sewage and how to claim if it is a new build
A sewage smell at home is one of the most unpleasant problems a property can have. It causes real concern because it is seen as something difficult to fix. That is not quite the case, but when it appears in the bathroom, in the kitchen or next to the washing machine,...
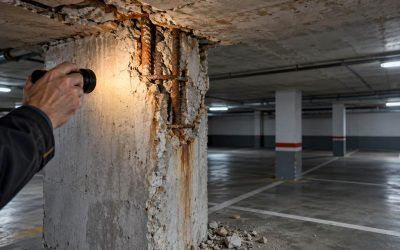
Structural Damage and Building Pathologies: What They Are, Examples and How to Claim Against the Building Contractor or Developer
A crack that widens every winter, a door that suddenly no longer closes, a floor slab that sags or a garage with spalling concrete and exposed reinforcement. Behind many of these symptoms lie structural damage and building pathologies: defects that originate in the...
Building contractor ordered to pay over €25,000 for defective flooring in a home
The Civil Division of the Court of First Instance of Jaén (Tribunal de Instancia, Plaza nº 3) has handed down Judgment no. 396/2026, dated 29 September 2026, fully upholding the claim brought by the owners of a home against the building contractor responsible for the...
DON’T HESITATE TO CONSULT US!
CUSTOM BUDGETS

0 Comments